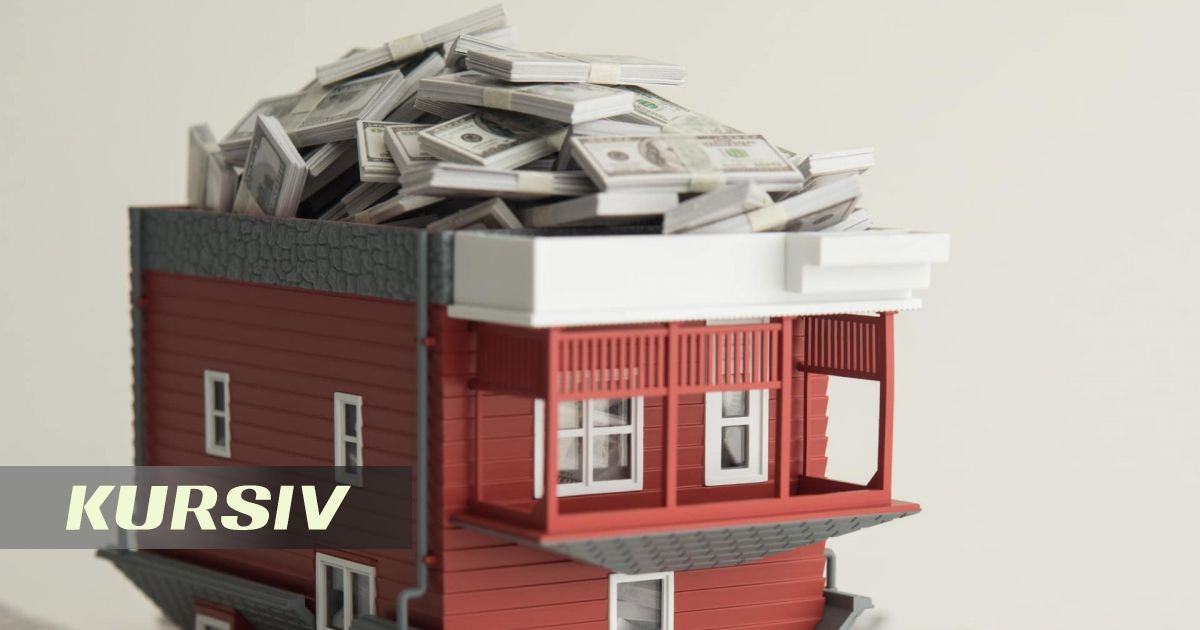
When a borrower dies, the mortgage is not automatically written off: if relatives accept the apartment as an inheritance, the loan obligations pass to them along with it. At the same time, the bank cannot demand early repayment of the entire mortgage solely because the client has died — this clarification was issued by the Agency for Regulation and Development of the Financial Market (ARDFM), according to infohub.kz.
The agency recalled that under Kazakhstan's Civil Code, heirs receive not only the deceased person's property but also their property rights and obligations. This also applies to mortgaged real estate, which remains pledged to the bank until the loan obligations are fully fulfilled.
After accepting the inheritance, relatives become joint debtors. The bank has the right to demand repayment from them, but each heir's liability is limited to the value of the property they received. For example, if the value of the inherited property is less than the remaining mortgage debt, the heir is not obligated to answer for the deceased's obligations beyond the value of that property.
Creditors may file claims not only against heirs but also against the executor of the will or the trustee managing the estate. If heirs have accepted the real estate but are avoiding registering their rights to it, the bank may demand that registration be carried out by force.
The borrower's death does not terminate the mortgage. The apartment remains pledged to the bank until the loan obligations are fulfilled. This means the bank retains the right to foreclose on the pledged real estate. However, such a procedure must be carried out in accordance with the law, the terms of the loan and mortgage agreements, and the circumstances of the specific case.
The mere fact of the borrower's death does not give the bank an unconditional right to demand early repayment of the entire debt. Such a demand is possible only in cases provided for by law and the bank loan agreement.
Six months from the opening of the inheritance are allotted for accepting an inheritance by law. During this period, the bank must consider suspending the accrual of interest, fines, penalties and other payments related to the overdue amount. This refers to the time needed to determine the circle of heirs and their entry into the inheritance. At the same time, ARDFM does not speak of an automatic cancellation of accruals — the bank must consider the relevant matter.
After the inheritance is accepted, mortgage payments continue in accordance with the loan agreement, the payment schedule and the mortgage agreement.
If there are no heirs by law or by will, no one has the right to inherit, or all heirs have renounced the inheritance, the property is deemed escheat. In that case, it passes into communal ownership at the place where the inheritance was opened. However, the deceased's debt to the bank does not disappear: the creditor retains the right to file claims in the manner and within the limits established by law.
If the deceased had co-borrowers, their obligations also remain in the amount provided for by the loan agreement. As for guarantees and sureties, they terminate together with the obligation they secured, unless the law or the agreement provides otherwise. Other grounds established by law for their termination also apply.
Earlier, Kursiv wrote that Kazakhstanis had mortgage debts worth 250 billion tenge written off.